
Open Interest Is Not a Queue of Buyers
Sixty contracts can trade while open interest ends exactly where it started. For wheel sellers, outstanding positions are not a promise of liquidity or an easy exit.
YieldCove Desk
2 min read
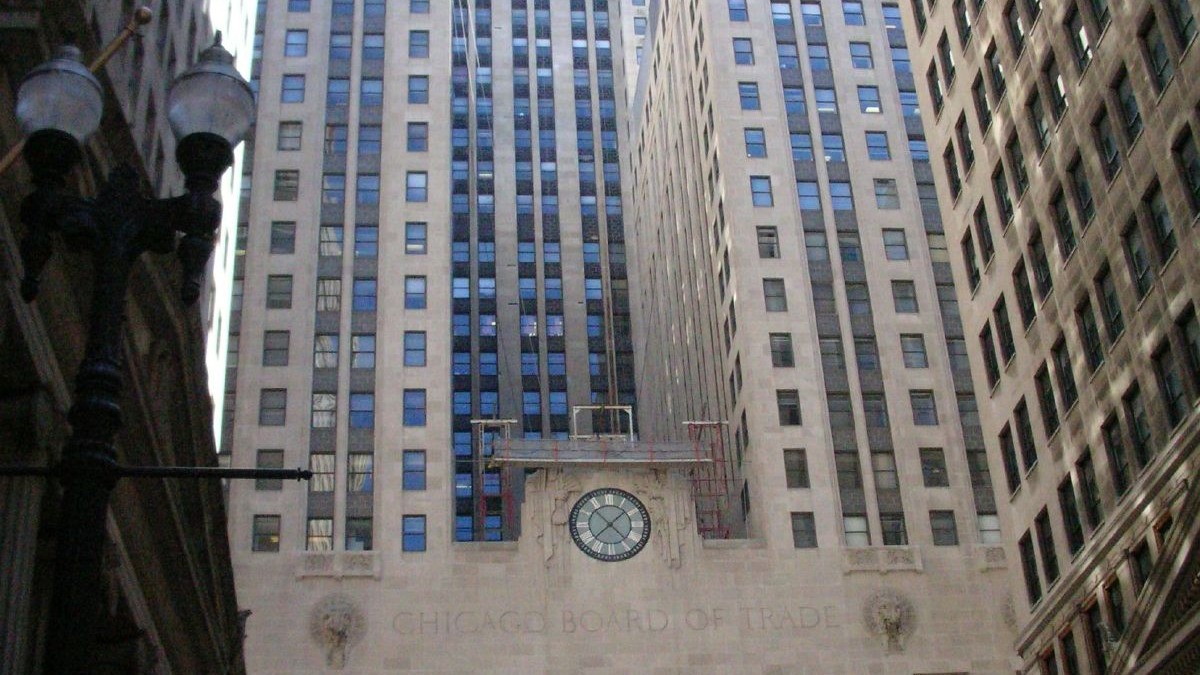
A busy option can change hands without creating any new outstanding contracts. Open interest is a count of contracts still open, not a queue of buyers waiting for a wheel seller. It does not promise an easy entry or exit.
Two counters, different questions
Trading volume counts contracts traded during a period. Open interest counts outstanding contracts in a particular option series: the same underlying, call or put, strike and expiration. One contract has a long side and a short side; it is not counted twice just because there are two counterparties. Higher open interest alone is neither a bullish nor a bearish signal. OIC: General Information
The clocks differ, too. OCC reports new open interest after clearing and pairing opening and closing positions at the end of the day. An intraday volume counter and the displayed open-interest figure therefore need not describe the same interval.
60 traded, zero net change
Suppose a series starts with 100 open contracts. In this hypothetical session, each group below trades 20 contracts. There are no other trades, exercises or expirations. Every number is a contract count—not shares, dollars or a premium quote.
Session volume
60
Ending open interest
100
Net OI change
0
| Transaction | OI change | OI total |
|---|---|---|
| Both sides open | +20 | 120 |
| One opens; one closes | 0 | 120 |
| Both sides close | −20 | 100 |
The middle group transfers an existing position: a new participant replaces one who exits, so open interest stays unchanged. Across the session, volume is 20 + 20 + 20 = 60, while open interest is 100 + 20 + 0 − 20 = 100. High activity and flat open interest can coexist; neither number alone identifies buyers waiting at a particular price.
What this means for the wheel
- Open interest can describe participation in the exact series. It cannot substitute for the current bid, ask and displayed contract sizes.
- A short put or covered call may need to be bought back. The price and size available on the ask side matter to that exit; a large open-interest number does not set the cost.
- A limit order specifies an acceptable price, not a guaranteed fill. A market order can reach less favorable price levels when its size exceeds the quantity available at the best quote.
Outstanding is not available
Use open interest as background about existing positions—not as a live order book, a direction forecast or an assurance of liquidity. The distinction matters both when collecting premium and when trying to close the obligation.
The execution distinction follows the OIC Trade Entry & Execution FAQ. This example models contract counts only; it estimates no premium, collateral requirement, return or probability of assignment.
Sources
- [1]General Information — open interest and liquidity — OCC / The Options Industry Council · Accessed 2026-09-16T14:17:21.558976+00:00 · Tier 1
- [2]Trade Entry & Execution — open interest and execution — OCC / The Options Industry Council · Accessed 2026-09-16T14:16:34.505174+00:00 · Tier 1
- [3]Chicago Board of Trade — photograph by Richie Diesterheft — Wikimedia Commons / Richie Diesterheft · Accessed 2026-09-16T14:18:55.866126+00:00 · Tier 1
- [4]Creative Commons Attribution 2.0 — license — Creative Commons · Accessed 2026-09-16T14:18:56.010329+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
More tips from the desk
At Expiration, the Closing Price Is Not Confirmation
Exercise-by-exception sets a default, not a guaranteed assignment outcome. One put example separates the closing price, the holder’s choice and the full cash payment if assigned.
Put Delta Is Not an Assignment Forecast
Delta estimates price sensitivity, not a promise about assignment. A −0.30 example separates a $30 price response from the full $5,000 purchase obligation.
AMZN wheel watch: $240 put, 8.5% cushion, 42 DTE
The September 4 snapshot illustrates an October 16 AMZN $240 put with $3.45 credit math and an 8.48% breakeven cushion. The historical three-month IV norm and confirmed earnings date are unavailable; this is not a fully qualified entry setup.