Key takeaways
- Corteva reported weaker crop-protection sales and updated its 2026 outlook on November 11.
- Brazil’s financing and inventory pressures outweighed growth elsewhere.
- The November 12 earnings call remains a live catalyst; a lower share price is not a safety cushion.
Nov 11 regular close
US$12.14
-0.25% versus Nov 10
After-hours snapshot
US$11.19
-7.82% from close; 19:32:59 EST
Nov 11 share volume
13,206,781
0.66× preceding 20-session average
30-day implied volatility
49.12%
Cboe snapshot retrieved 19:33 EST; not live
Next results release
Unconfirmed
Q3 results released November 11
Next earnings call
Nov 12, 10:30 EST
2026; results and outlook discussion
A quiet close, then an earnings shock
Corteva’s November 11 results put Brazil’s crop-protection slowdown at the centre of its outlook. The company reported US$1.591 billion of third-quarter pro-forma sales, down 9% year over year, and adjusted pro-forma operating EBITDA of US$222 million, down 17%. These are results for the quarter ended September 30, not estimates for the coming quarter. Issuer release
The stock had closed the regular session at US$12.14, down US$0.03, or 0.25%, from November 10. In the saved Yahoo Finance observation timestamped 19:32:59 EST, the extended-hours price was US$11.1904, displayed here as US$11.19: a 7.82% decline from the unrounded regular close. The snapshot was retrieved at 19:34 EST; it is historical, indicative data, not a live trading quote. Daily data Extended hours
Regular-session volume was 13,206,781 shares in our 19:33 EST retrieval, compared with an average of 20,129,430 over the preceding 20 sessions, October 14–November 10. That is 0.66 times the average. It describes trading before the earnings release, not the intensity of the later selloff.
Read the new company, not the old consolidated business
Corteva completed the spin-off of its seed and genetics business on October 1, becoming a focused crop-protection company. That makes the accounting labels important: this release presents the new business on a pro-forma basis, with additional adjustments for its operating measures. Comparing these figures with an old combined seeds-and-chemicals headline would mix different businesses. Separation announcement
| Measure | Reported figure | Basis / comparison |
|---|---|---|
| Q3 sales | US$1.591 billion | Pro forma; -9% year over year |
| Q3 continuing-operations loss | US$54 million | Pro-forma GAAP; US$60m profit a year earlier |
| Q3 operating EPS | US$0.06 | Adjusted pro forma, non-GAAP; -57% |
| Q3 operating EBITDA | US$222 million | Adjusted pro forma, non-GAAP; -17% |
| 2026 operating EBITDA outlook | US$1.100–1.125 billion | Adjusted pro forma, non-GAAP |
| 2026 operating EPS outlook | US$0.76–0.80 | Adjusted pro forma, non-GAAP |
The pro-forma GAAP loss from continuing operations was US$54 million, versus a US$60 million profit a year earlier. Adjusted pro-forma operating EPS was US$0.06, down 57%; it is not GAAP EPS. Management’s full-year ranges are forecasts, and the company says it cannot reconcile its forward-looking non-GAAP measures to GAAP without unreasonable effort.
Why Brazil matters more than the global headline
The weak spot was not uniform demand everywhere. Latin American organic sales fell 31%, with volume down 24% and pricing down 7%; North American organic sales rose 7%, EMEA rose 14%, and Asia Pacific rose 5%. Organic sales exclude currency and portfolio effects, so those regional percentages are not interchangeable with reported sales growth.
- Brazil: management cited farmer liquidity constraints, high financing costs, elevated channel inventory and delayed purchasing.
- Product mix: competition in mature molecules and U.S. acetochlor pricing pressured sales, despite demand for new products.
- Company-wide: quarterly volume fell 2% and pricing fell 7%; growth outside Latin America did not offset Brazil.
FMC is a useful crop-protection peer, but its share performance cannot prove why Corteva moved. FMC finished November 11 at US$5.65, up 0.18%, while Corteva’s regular-session decline was 0.25%; both readings precede Corteva’s 16:30 EST release. The contrast separates the daytime sector backdrop from the subsequent company-specific earnings reaction. FMC business FMC market data
Crop-protection peers before Corteva’s release
November 11, 2026 regular-session close-to-close returns; excludes after-hours trading.
Source: Yahoo Finance CTVA/FMC daily data, retrieved November 11, 2026 at 19:33 EST; returns calculated from unrounded closes.
A smaller share price does not make the business risk smaller.
What it means for option sellers
Cboe’s snapshot retrieved at 19:33 EST displayed 30-day implied volatility of 49.119%, rounded here to 49.12%. That observation does not establish live post-release option prices, and a comparable IV rank was not verified. Without a verified current chain, this article makes no claim about available premiums, delta, liquidity or the market-implied earnings move. Cboe snapshot
The wheel starts with a possible obligation to buy shares through put assignment; a covered call instead can require selling shares at its strike. A premium cannot prevent a loss when the underlying falls sharply. Following the separation, an actual contract’s deliverable must be checked rather than assuming every older contract represents only 100 Corteva shares. Cash-secured put Covered call
Educational arithmetic — not a quoted trade
Assume a new, unadjusted 100-share US$10 put and an entirely hypothetical US$0.20-per-share credit. Gross credit would be US$20, strike cash US$1,000 and breakeven US$9.80 before fees; a zero share price would mean a US$980 loss. A hypothetical US$13 covered call caps the sale price at US$13 if assigned; neither strike is a recommendation or a confirmed available contract.
The report is out; the event risk is not over
The November 12 call can add information about Brazil, pricing and the outlook. After-hours share prices do not guarantee next-session executions, and elevated implied volatility is compensation for uncertainty, not a promised return.
Risks and review plan
- Downside: further Brazil weakness, pricing pressure or new guidance changes could outweigh the premium collected.
- Contract risk: check post-separation deliverables and live liquidity; the educational example does not validate an older adjusted contract.
- Review plan: reassess the thesis after the November 12 call, including the cash needed for put assignment and the sale obligation of a covered call.
What to watch next
- November 12, 10:30 EST: the earnings call and questions on Brazil’s inventory, farmer financing and purchasing patterns.
- After the call: compare management’s detail with the US$1.100–1.125 billion EBITDA and US$0.76–0.80 EPS outlook, preserving the adjusted pro-forma basis.
- Before any options decision: refresh live quotes, spreads and contract terms; review assignment affordability and the next confirmed earnings date. That next results date remains unconfirmed here.
The practical question is whether pressure in Brazil stabilizes, not whether a lower price looks cheaper than yesterday. Management describes demand outside Latin America as resilient, but that does not guarantee a recovery or remove the possibility of further guidance changes. The call is scheduled for November 12 at 10:30 EST. Results and call details
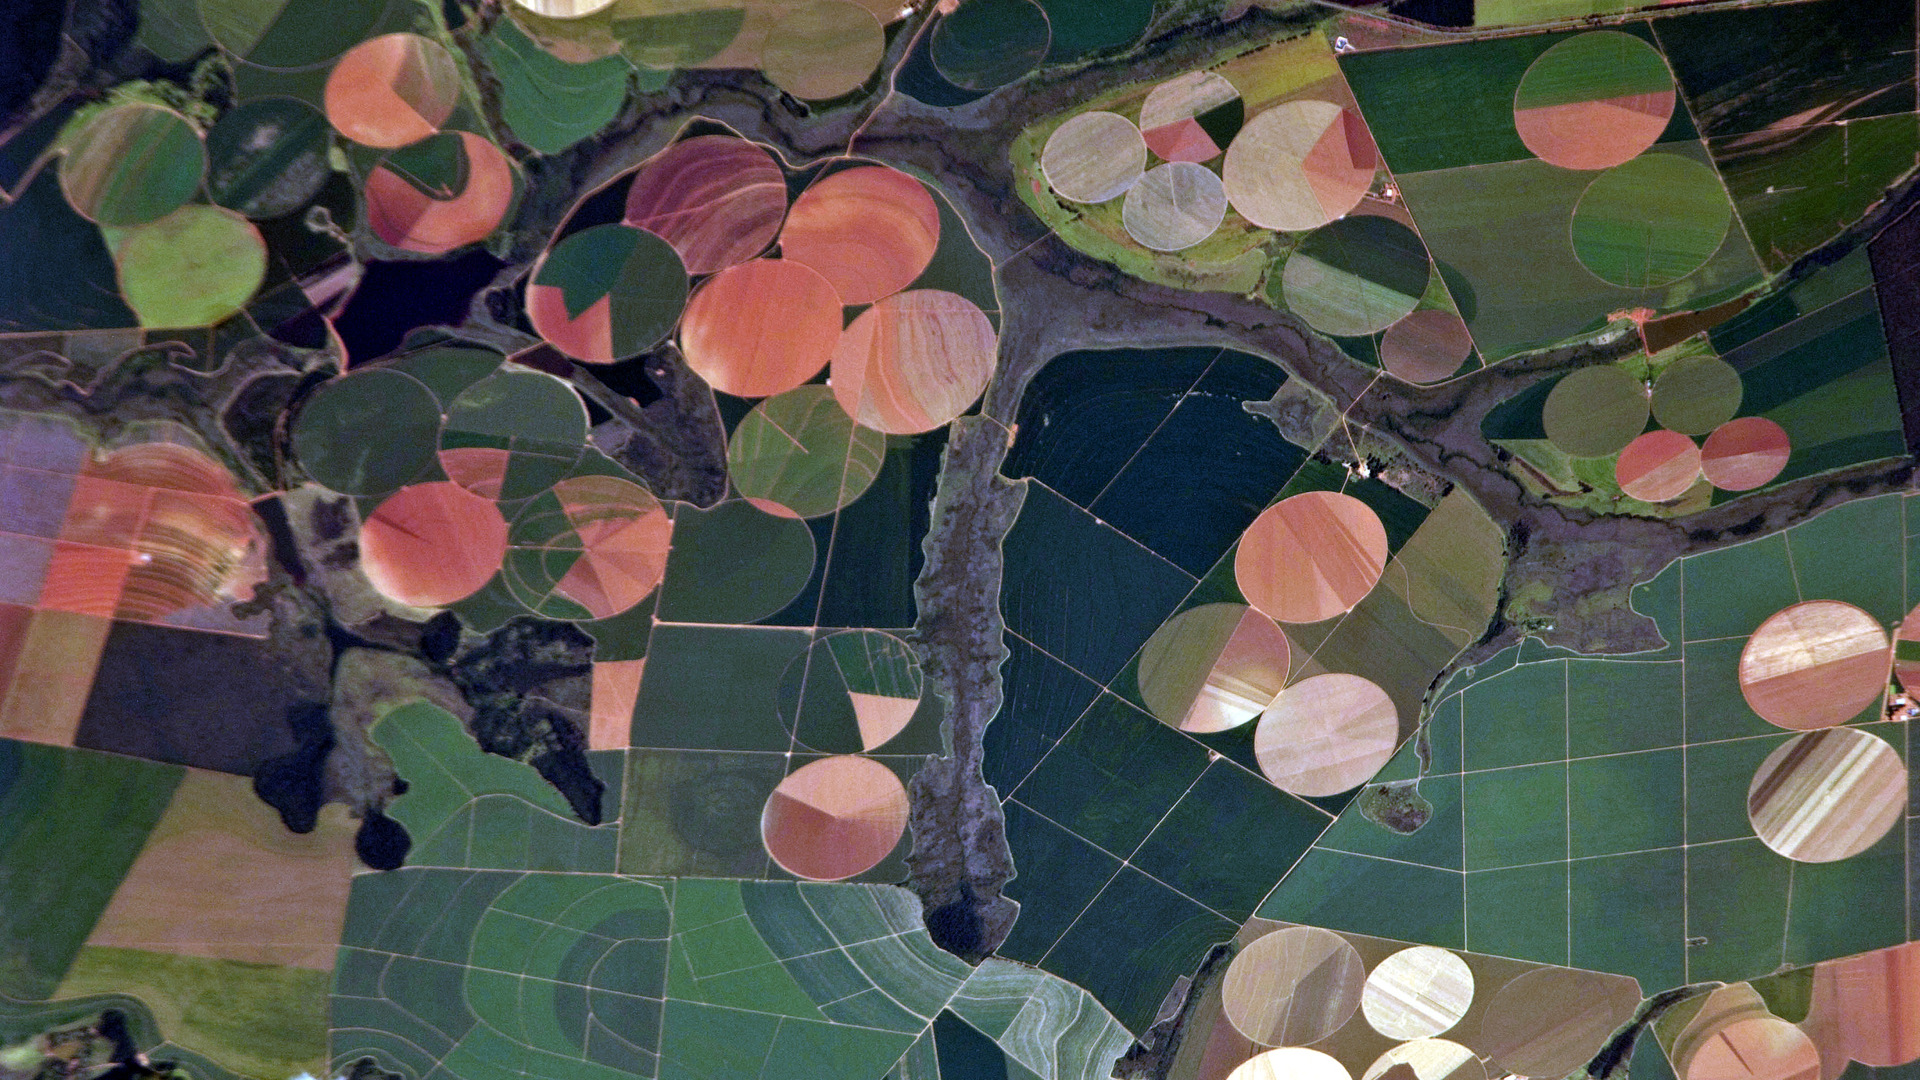
Hero: NASA / ISS Expedition 26 crew, public domain, via Wikimedia Commons; photographed near Perdizes, Brazil, on February 10, 2011. The image is cropped and resized, with no generative edits here. It illustrates agriculture, not identified Corteva property or present crop conditions; NASA’s editorial-use guidance applies without implying endorsement.
Sources
- [1]Q3 2026 results and updated outlook; release 16:30 EST — Corteva, distributed by PR Newswire · Accessed 2026-11-12T00:33:22.184546+00:00 · Tier 1
- [2]October 1, 2026 seed-business separation — Corteva · Accessed 2026-11-12T00:49:28.446196+00:00 · Tier 1
- [3]CTVA daily prices and volume; retrieved November 11, 19:33 EST — Yahoo Finance · Accessed 2026-11-12T00:33:22.553538+00:00 · Tier 3
- [4]CTVA extended-hours snapshot; 19:32:59 EST, November 11 — Yahoo Finance · Accessed 2026-11-12T00:34:30.260150+00:00 · Tier 3
- [5]FMC daily prices; retrieved November 11, 19:33 EST — Yahoo Finance · Accessed 2026-11-12T00:33:22.549987+00:00 · Tier 3
- [6]About FMC: crop-protection business — FMC Corporation · Accessed 2026-11-12T00:34:30.233831+00:00 · Tier 1
- [7]CTVA 30-day IV snapshot; retrieved November 11, 19:33 EST — Cboe · Accessed 2026-11-12T00:33:22.472507+00:00 · Tier 1
- [8]Cash-secured put strategy and risks — Options Industry Council · Accessed 2026-11-12T00:33:22.432963+00:00 · Tier 1
- [9]Covered call strategy and risks — Options Industry Council · Accessed 2026-11-12T00:33:22.454348+00:00 · Tier 1
- [10]Agricultural fields near Perdizes, Brazil: photograph and public-domain notice — NASA / Wikimedia Commons · Accessed 2026-11-12T00:19:59.956552+00:00 · Tier 1
- [11]NASA images and media-use guidance — NASA · Accessed 2026-11-12T00:19:59.970855+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
Keep YieldCove close
Choose YieldCove as a preferred source for Top Stories in Google Search.
Run the numbers before you trade: the free wheel strategy calculator sizes the whole cycle, and the cash-secured put calculator shows the cash, return and breakeven of one put.