
AI’s next test: financing, efficiency and three wheel setups
A mixed inflation signal, Micron’s labor risk and the case for patience before the Fed.
SATURDAY · SEPTEMBER 12, 2026
Weekend briefing · Research cutoff: 06:15 Toronto. Market data: September 11 close. Dollar amounts are U.S. dollars unless stated.
The morning brief
- Inflation accelerated month to month, while annual core inflation eased. The AI trade still needs to pass the financing test. [1–2]
- Micron’s employee rewards, school AI safeguards and cheaper model delivery show three different constraints on growth. [3–8]
- Three wheel scenarios: Alphabet needs trend repair, Microsoft needs confirmation, and Credo remains a pass. Reprice every contract at the next market open.
The lead · AI’s next hurdle is the cost of capital
Friday’s U.S. inflation release offers a mixed starting point for next week. August headline CPI rose 0.4% month to month, versus 0.1% in July; core rose 0.3%, versus 0.2%. Yet annual core inflation eased to 2.4% from 2.5%. These measures describe different windows, so a cooler annual reading does not erase the faster monthly pace. [1–2]
Our interpretation: AI investors should separate technological progress from the price of financing it. A more capable model can attract customers while a data-center project still struggles to justify its construction bill. Higher required returns make distant cash flows less valuable today. That matters most where spending comes early and dependable customer payments arrive much later. The question is whether utilization, contract quality and operating cash can support the expansion without repeated dilution.
There is a credible counterargument: cheaper inference can unlock applications that were previously uneconomic, spreading adoption and supporting infrastructure demand. Efficiency does not mechanically mean fewer chips; usage can grow enough to offset lower compute per task. Neither outcome is guaranteed. Ahead of the September 16 Fed decision, favor evidence of paid demand, funding capacity and disciplined entry prices over a single inflation headline or benchmark ranking. [7–8,11]
Eddie’s watchlist · Three signals to carry into next week
- MU · Labor remains a production risk. On September 11, Micron announced Taiwan rewards equivalent to 35–68 months’ pay. Reuters reports the Taoyuan union still had no agreement. Our lens: watch negotiations and operating continuity; a large payout is not proof that disruption risk has disappeared. The September 30 earnings call is the next confirmed reporting checkpoint. [3–4,12]
- MSFT · Adoption needs procurement confidence. The September 9 Microsoft/AFT/UFT agreement lets U.S. school districts incorporate AI safeguards into customer contracts. This is recent context, not a fresh Friday launch. Our lens: clearer rules may ease purchasing decisions, but signed protections do not establish incremental revenue. Watch implementation and renewal rather than announcement volume. [5]
- CRDO · Guidance is a test, not booked sales. X discussion renewed attention to Credo’s September 1 outlook: Q2 revenue of $525–535 million. That remains a company forecast. Our lens: follow delivery and margins together; network demand can grow while execution or valuation disappoints. The wheel card below explains why attractive technology can still be an unattractive setup. [6]
AI buildout & revolution
DeepSeek · Efficiency moves into the memory stack. September 10’s V4.1 Flash release adds native visual understanding. DeepSeek reports its KV cache requires one-quarter of the previous generation’s HBM and one-eighth of its SSD storage. These are vendor claims about cache requirements, not total system demand. Our lens: lower serving costs could broaden agent usage; test cost per successful task, including retries, before extrapolating benefits to chip suppliers. [7]
Sakana · Choosing the model becomes part of the product. September 11’s Fugu Max and Ultra v2 release routes work across model pools. Max emphasizes cost; Ultra emphasizes capability. Our lens: orchestration could create value by matching task difficulty to the resources used. Vendor benchmarks are not independent customer economics. Watch reliability, latency and the full bill for completed work, rather than the cheapest advertised token. [8]
One comparison · Faster monthly inflation, cooler annual core
| Measure | July | August |
|---|---|---|
| Headline · monthly | 0.1% | 0.4% |
| Core · monthly | 0.2% | 0.3% |
| Core · year over year | 2.5% | 2.4% |
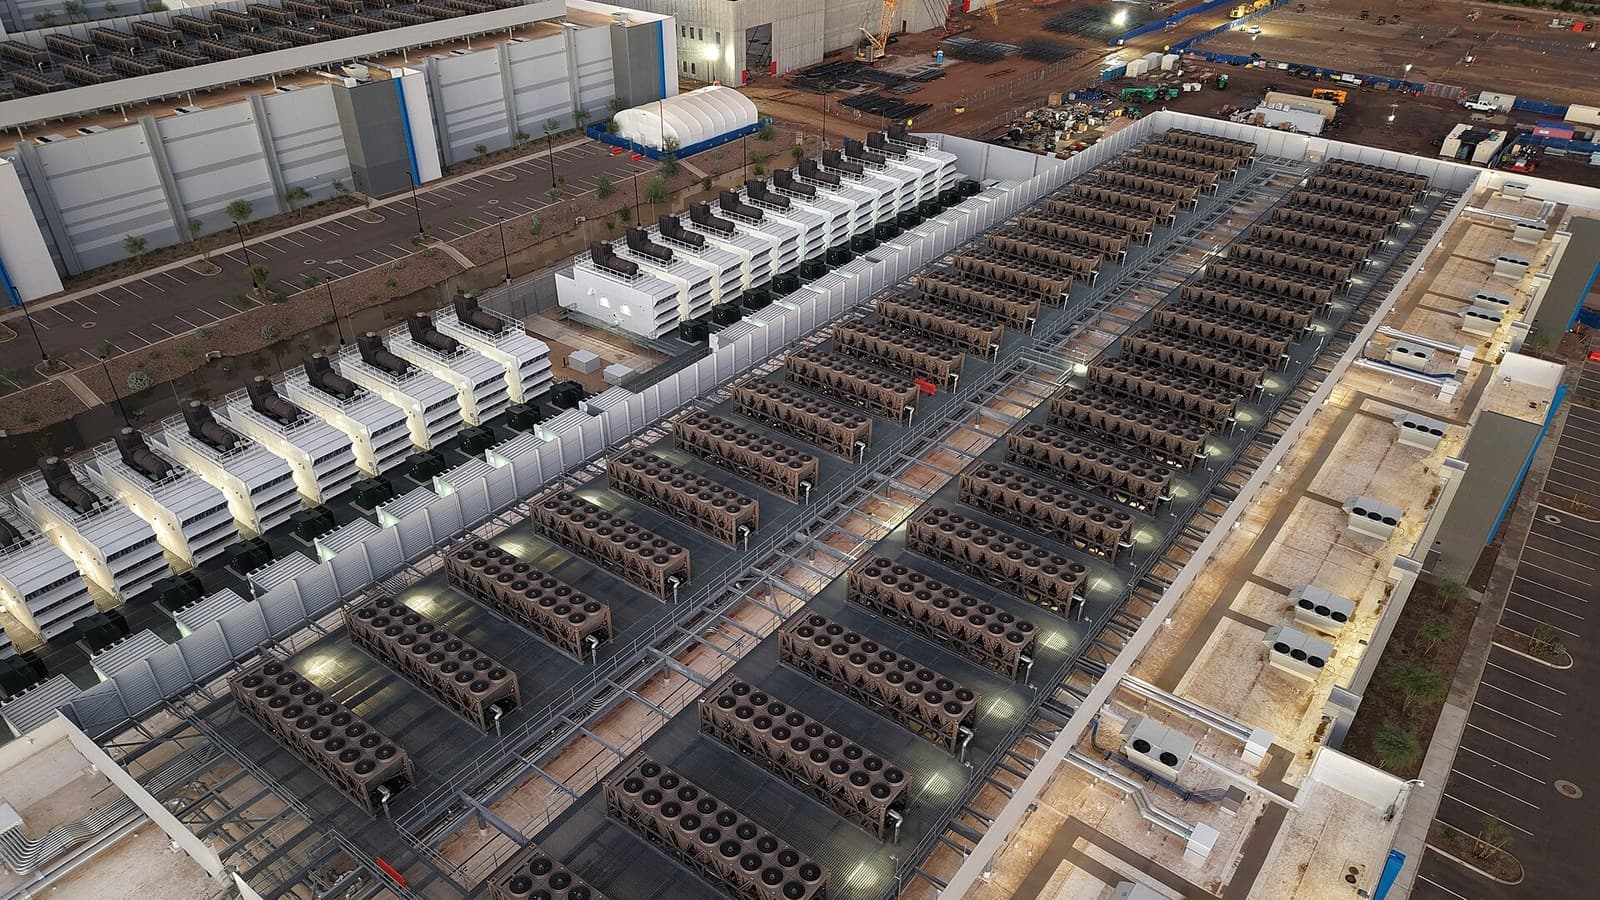
The annual core rate fell 0.1 percentage point; the monthly headline rate increased 0.3 point. Different horizons can move in opposite directions. The photograph illustrates data-center cooling and backup power; no featured company’s facility is identified. Photo: Rsparks3, CC0. [1,13]
3 Wheel Trade Ideas
Three scenarios, with conditions
Cash-secured puts · October 16, 2026 expiry, 34 days. September 11 closes and last option trades; delayed Cboe snapshots retrieved today around 06:04 Toronto. Exact bid/ask timestamps and open-interest dates are unspecified. Reprice at the open. Standard 100-share deliverables assumed; confirm with your broker. Figures exclude fees/taxes.
GOOGL · $320 put · Conditional on trend repair
Educational scenario · No fill assumed
- Why wheel: Q2 operating margin of 34% supports an ownership case, but quarterly FCF was −$5.855bn. At $315.75 effective entry, investment gains distort headline EPS; do not infer cheapness from reported P/E. Rate-sensitive capex remains central. [9]
- Technicals: close $338.50; RSI14 46.9; SMA20/50/200 $340.89/$346.98/$336.38; volume 1.09×. Below shorter averages, barely above SMA200; not oversold. [15]
- Contract: Oct 16 $320 put; bid/ask $4.25/$4.45, delta −0.2375, IV 28.80%; volume/OI 825/7,799. Cash $32,000; indicative bid credit $425; breakeven $315.75. [16]
- Wait / invalidate: require recovery above SMA50; a break below SMA200 weakens support. Cash-flow recovery and a normalized valuation check must precede any entry. [9,15]
MSFT · $470 put · Conditional on confirmation
Educational scenario · No fill assumed
- Why wheel: enterprise AI exposure with FY2026 operating cash flow of $182.935bn against $115.948bn cash capex. Entry $464.95 equals 25.9× FY GAAP EPS, including investment gains: a valuation reference, not a bargain verdict. [10]
- Technicals: close $495.63; RSI14 56.9; SMA20/50/200 $494.25/$453.12/$429.65; volume 0.68×. Above all averages, but participation is weak. [17]
- Contract: Oct 16 $470 put; bid/ask $5.05/$5.30, delta −0.2222, IV 25.27%; volume/OI 444/4,830. Cash $47,000; indicative bid credit $505; breakeven $464.95. [18]
- Wait / invalidate: require SMA20 support and stronger volume after the Fed; a break below SMA50 weakens the thesis. The strike sits above that longer support. [11,17]
CRDO · $150 put · Pass for now
Educational scenario · No fill assumed
- Why wheel: AI connectivity has an ownership rationale, but Q1 GAAP operating margin fell to 25.2% from 35.7% sequentially. Entry $143 is 53.4× annualized quarterly GAAP EPS; that simple screen is not a forecast or cheapness signal. [6]
- Technicals: close $162.95; RSI14 33.2; SMA20/50/200 $211.29/$223.10/$175.89; volume 0.83×. Below every average; near oversold, without a confirmed reversal. [19]
- Contract: Oct 16 $150 put; bid/ask $7.00/$7.20, delta −0.3014, IV 65.91%; volume/OI 210/2,068. Cash $15,000; indicative bid credit $700; breakeven $143. [20]
- Pass / reconsider: wait for SMA200 recovery and verify current cash-flow conversion. High IV does not repair the downtrend; a fresh low or weaker margins undermines the case. [6,19]
Shared checks: losses if shares fall to zero are $31,575 / $46,495 / $14,300; early assignment is possible. Next earnings/ex-dividend dates and IV rank remain unconfirmed: verify before execution. September 16’s Fed decision precedes expiry. Delta is not an assignment guarantee. Daily Wilder RSI14 and SMAs use adjusted closes; volume compares the completed session with its prior 20-session mean. [11,14–24]
Next on the radar
- September 14 · 00:00 Toronto: DeepSeek says V4-Pro API requests switch to V4.1 Flash; check workflow quality after migration. [7]
- September 16 · 14:00 Toronto: Fed decision; reassess funding and valuation assumptions. [11]
- September 30 · 16:30 Toronto: Micron earnings call; watch supply continuity and the memory outlook. [12]
From YieldCove
Compare assignment cash and breakeven in the options calculator. Start with an ownership decision; let the premium inform the terms.
Sources
- [1]August CPI — September 11 release — U.S. Bureau of Labor Statistics · Accessed 2026-09-12 · Tier 1
- [2]August inflation and the monetary-policy backdrop — Reuters / Investing.com · Accessed 2026-09-12 · Tier 2
- [3]Micron announces Taiwan employee rewards — CNA / Focus Taiwan · Accessed 2026-09-12 · Tier 2
- [4]Micron rewards and unresolved union negotiations — Reuters / MarketScreener · Accessed 2026-09-12 · Tier 2
- [5]School AI safety and privacy agreement — September 9 — Microsoft · Accessed 2026-09-12 · Tier 1
- [6]Credo Q1 FY2027 results — Credo · Accessed 2026-09-12 · Tier 1
- [7]DeepSeek V4.1 Flash launch and API migration — DeepSeek · Accessed 2026-09-12 · Tier 1
- [8]Fugu Max and Ultra v2 launch — Sakana AI · Accessed 2026-09-12 · Tier 1
- [9]Alphabet Q2 2026 results — Alphabet / SEC · Accessed 2026-09-12 · Tier 1
- [10]Microsoft FY2026 Q4 and full-year results — Microsoft · Accessed 2026-09-12 · Tier 1
- [11]September policy calendar — Federal Reserve · Accessed 2026-09-12 · Tier 1
- [12]Micron September 30 earnings call — Micron · Accessed 2026-09-12 · Tier 1
- [13]Data center roof — photo and CC0 license — Wikimedia Commons / Rsparks3 · Accessed 2026-09-12 · Tier 1
- [14]Cash-secured put mechanics and risks — Options Industry Council · Accessed 2026-09-12 · Tier 1
- [15]GOOGL daily price history — Yahoo Finance · Accessed 2026-09-12 · Tier 2
- [16]GOOGL delayed option chain — Cboe · Accessed 2026-09-12 · Tier 1
- [17]MSFT daily price history — Yahoo Finance · Accessed 2026-09-12 · Tier 2
- [18]MSFT delayed option chain — Cboe · Accessed 2026-09-12 · Tier 1
- [19]CRDO daily price history — Yahoo Finance · Accessed 2026-09-12 · Tier 2
- [20]CRDO delayed option chain — Cboe · Accessed 2026-09-12 · Tier 1
- [21]Microsoft earnings calendar — Microsoft · Accessed 2026-09-12 · Tier 1
- [22]Microsoft latest declared dividend — Microsoft · Accessed 2026-09-12 · Tier 1
- [23]Credo event calendar — Credo · Accessed 2026-09-12 · Tier 1
- [24]Alphabet investor calendar — Alphabet · Accessed 2026-09-12 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
The free YieldCove newsletter
Get The Wheelhouse in your inbox
Three briefings a week — market context, practical wheel-strategy ideas and YieldCove updates. Free to read. Unsubscribe anytime.
Educational only — not financial advice.