
Oil’s new shock tests the AI trade before the Fed
Oil is rising while the AI growth story faces a new safety debate before the Fed decision. For premium sellers, richer compensation comes with inflation, spending and assignment risks—not an automatic bargain.
YieldCove Desk
3 min read
S&P 500 futures · Dec.
−0.67%
Nasdaq-100 futures · Dec.
−1.61%
Brent · USD/barrel
107.62
+2.88%
VIX · early session
17.64
A fresh oil shock and a debate over slowing frontier AI are testing the growth trade before the Federal Reserve’s decision. The central question is whether a more expensive energy bill collides with weaker confidence in the pace of technology spending. For option sellers, a larger premium is compensation for that uncertainty, not evidence that the underlying shares became safer.
Snapshot: September 14, 2026, around 04:00–04:10 America/Toronto (EDT); Asian and European indices retain their earlier local observation times. Futures are delayed observations, not executable prices, and the equity contracts above expire in December. Friday’s completed data are identified separately. [1–4]
Macro overnight
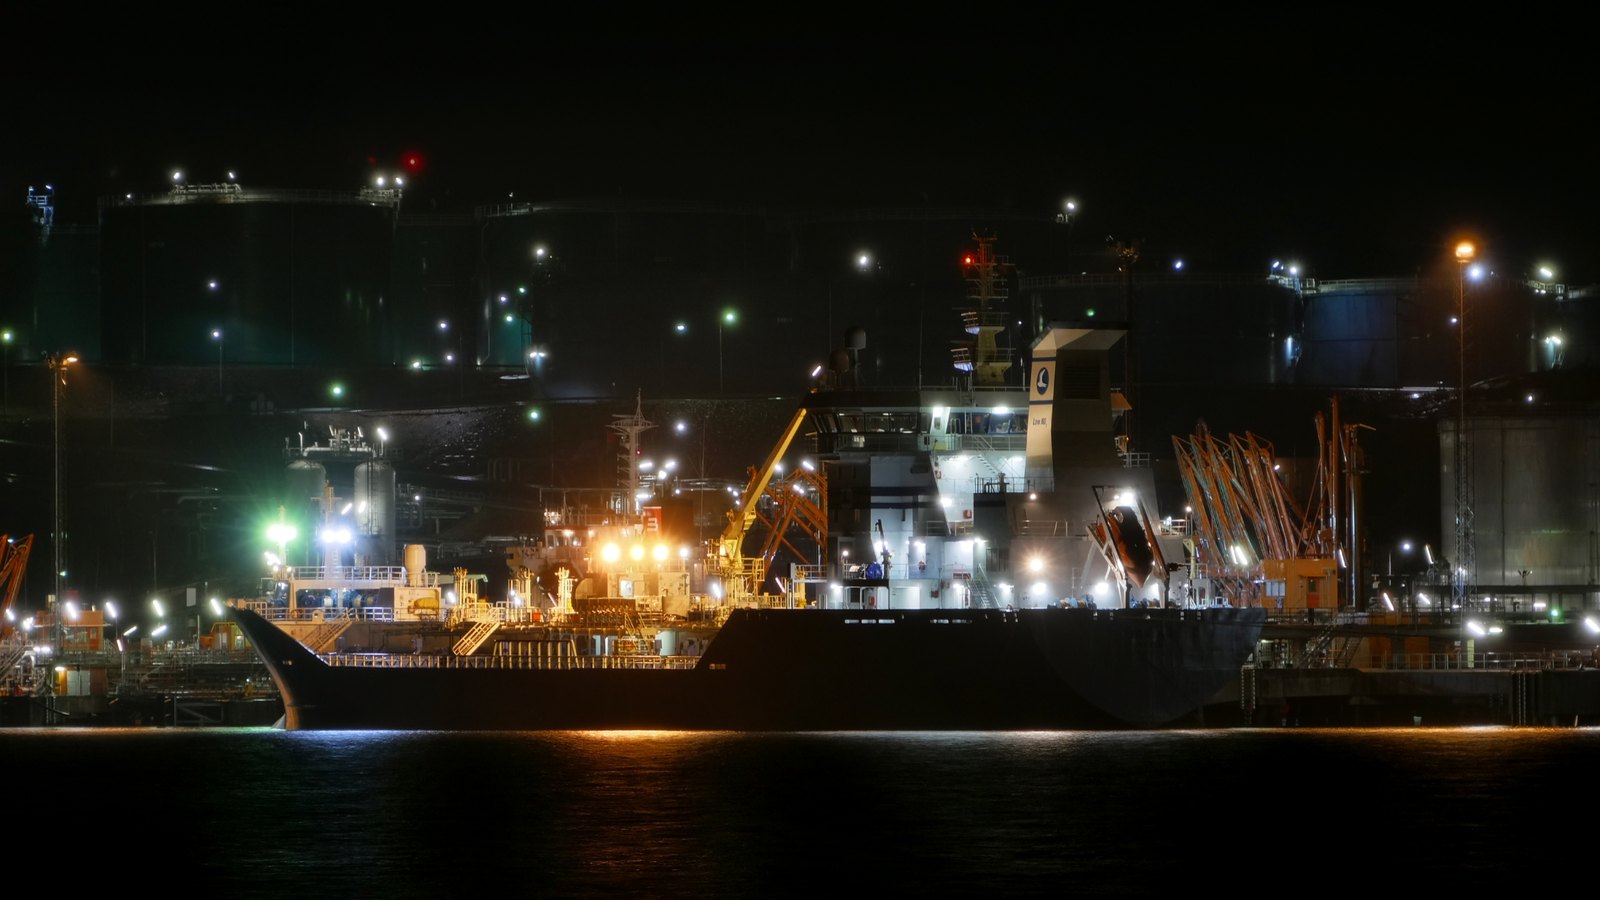
Oil is the immediate inflation channel. Saudi Arabia’s East-West pipeline was closed after attacks, while the planned Oman meeting on Gulf shipping was postponed; the shutdown’s duration remains uncertain. This matters because a route that bypasses the Strait of Hormuz cannot provide the same relief while it is shut. Brent and WTI were both above USD 100 per barrel in the early snapshot. [1,3,8,9]
The inflation backdrop is more nuanced than a simple acceleration story. August’s headline CPI rose 0.4% month on month, versus 0.1% in July; core CPI rose 0.3%, versus 0.2%. Yet annual core inflation eased to 2.4% from 2.5%, while headline inflation was 3.4%. Monthly figures are seasonally adjusted; annual figures are not. Fresh energy pressure therefore lands on firmer monthly prices without proving that every underlying inflation measure is worsening. [5]
| Market | Observation |
|---|---|
| WTI · Oct. | USD 102.65/barrel |
| Gold · Dec. | USD 4,351.60/oz |
| Dollar index | 99.55 |
| U.S. 2-year yield | 4.622% |
| U.S. 10-year yield | 4.965% |
| Nikkei / Kospi | −0.81% / −3.26% |
| Hang Seng | +0.36% |
| FTSE 100 / DAX | +0.35% / −0.65% |
Asia was not uniformly weak: Korea’s decline and Japan’s loss contrasted with a positive Hong Kong reading. Europe also split between a firmer FTSE and a weaker DAX. Gold futures were lower despite the geopolitical stress, alongside a firmer dollar. That combination is a reminder that a geopolitical shock does not automatically lift every defensive asset; financing costs and the currency backdrop still matter. [1,3,4]
Shorter Treasury yields rose faster over the week
Completed daily par yields; not intraday quotes. [6]
Source: U.S. Treasury · 2026-09-04 and 2026-09-11 [6]
The curve shows where policy pressure accumulated: from September 4 to September 11, the 2-year yield gained 26 basis points and the 10-year gained 18. The shorter end rose faster, narrowing the gap between those maturities. Higher collateral yields help cash earn something, but they do not offset the loss automatically if assigned shares fall. Meanwhile, the early VIX reading exceeded Friday’s official 15.84 close; index-level anxiety is not a substitute for a specific option’s bid, ask and event exposure. [1,4,6,7]
The AI debate is the second pressure point. Anthropic chief Dario Amodei is calling for a slower advance at the frontier and committing to embedded external evaluators. His essay explicitly distinguishes pacing from halting training or technical progress. The useful distinction for investors is between a safety proposal and an announced reduction in orders: the proposal itself is not a cancellation notice for chips or cloud capacity. The spending implications depend on what companies and governments actually implement. [10]
Your tickers
GWAV — Greenwave: A filing submitted after Friday’s U.S. close disclosed that its convertible-preferred placement closed on September 9, raising USD 3.75 million before fees; the initial conversion price is USD 5.24. Fresh funding comes with potential common-share dilution, not a USD 3.75 million addition to earnings. [11]
What to watch today
For September 14, the BLS release calendar and the New York Fed’s national calendar show no listed release. That is a quieter scheduled-data day, not a quiet risk day: oil-route developments and concrete responses to the AI proposal remain the moving pieces. The next scheduled checkpoints are the Empire State manufacturing survey on September 15 at 08:30 and retail sales on September 16 at 08:30, all America/Toronto. [12–14]
The FOMC meets September 15–16, with projections scheduled alongside the meeting. September 14 falls inside its monetary-policy communications blackout; this does not prohibit every public appearance. The decision has not happened yet. Until then, the central tension is between an oil-driven inflation risk and the durability of growth spending—not a demonstrated bargain in option premiums. [15,16]
Sources
- [1]Market snapshot: futures, global indices, currencies and Treasury yields — CNBC · Accessed 2026-09-14T08:10:51.283015+00:00 · Tier 2
- [2]December equity futures quotes — TradingView · Accessed 2026-09-14T08:13:21.688656+00:00 · Tier 2
- [3]Energy and gold futures quotes — TradingView · Accessed 2026-09-14T08:10:51.204789+00:00 · Tier 2
- [4]Global equity indices, dollar and Treasury yields — TradingView · Accessed 2026-09-14T08:10:51.208662+00:00 · Tier 2
- [5]Consumer Price Index — August 2026 — U.S. Bureau of Labor Statistics · Accessed 2026-09-14T08:10:51.289183+00:00 · Tier 1
- [6]Daily Treasury par yield curve rates — 2026 — U.S. Treasury · Accessed 2026-09-14T08:11:09.438898+00:00 · Tier 1
- [7]VIX daily closing history — Cboe · Accessed 2026-09-14T08:10:51.307362+00:00 · Tier 1
- [8]Oil rises after Saudi pipeline closure — CNBC · Accessed 2026-09-14T08:13:21.663102+00:00 · Tier 2
- [9]Shares slip in Asia as oil climbs — Reuters via MarketScreener · Accessed 2026-09-14T08:10:51.896088+00:00 · Tier 2
- [10]We Must Pace the Frontier — Dario Amodei · Accessed 2026-09-14T08:15:21.662435+00:00 · Tier 1
- [11]Current report: Series B financing — Greenwave / SEC · Accessed 2026-09-14T08:13:21.462735+00:00 · Tier 1
- [12]September 2026 release calendar — U.S. Bureau of Labor Statistics · Accessed 2026-09-14T08:10:51.230950+00:00 · Tier 1
- [13]National economic calendar — September 2026 — Federal Reserve Bank of New York · Accessed 2026-09-14T08:10:51.431466+00:00 · Tier 1
- [14]Economic indicators release calendar — U.S. Census Bureau · Accessed 2026-09-14T08:10:51.448731+00:00 · Tier 1
- [15]FOMC meeting calendars — Federal Reserve · Accessed 2026-09-14T08:10:51.348747+00:00 · Tier 1
- [16]FOMC external communications policy — Federal Reserve · Accessed 2026-09-14T08:13:21.703341+00:00 · Tier 1
- [17]Featured photograph — Preemraff Lysekil petroleum terminal — W.carter / Wikimedia Commons · Accessed 2026-09-14T08:22:04.474217+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
Read next

Cheaper oil lifts futures, but Japan adds another rate hurdle
Falling oil and stronger equity futures extend the relief rally even as Japan tightens monetary policy. For premium sellers, calmer broad-market volatility must still be weighed against elevated bond yields and company-specific risks.
Futures rebound, but the Fed keeps the funding hurdle high
Equity futures are recovering as oil and volatility ease after the Fed’s rate increase. For premium sellers, the rebound does not erase higher financing costs or the distinction between cash yield and compensation for assignment risk.
Oil eases, but 5% Treasuries keep the Fed-day pressure on
A modest rebound in equity futures is running into stubbornly high bond yields before the Fed decision. For premium sellers, the distinction between temporary oil relief and lasting policy risk matters more than a greener opening screen.