
Cheaper oil lifts futures, but Japan adds another rate hurdle
Falling oil and stronger equity futures extend the relief rally even as Japan tightens monetary policy. For premium sellers, calmer broad-market volatility must still be weighed against elevated bond yields and company-specific risks.
YieldCove Desk
4 min read
BOJ announced target [1]
1.25%
Nasdaq futures [3,4]
+0.64%
Brent · USD/barrel [3,4]
102.55
VIX · points [3,5]
15.16
Cheaper oil is giving equity futures room to extend their rebound, but the central-bank backdrop is still tightening. Japan’s latest decision is a reminder that relief in market prices is not the same thing as an easier cost of money, and a calmer volatility index does not remove company-specific risk.
Morning Read — September 18, 2026. U.S. equity, Brent and gold futures below are delayed observations at 03:58 EDT; yields, the dollar and VIX are observations at 04:07–04:08 EDT. Asia and Europe carry their own timestamps. These snapshots describe the overnight backdrop, not executable prices. The BOJ’s announced target takes effect on September 24. [1,3–5]
Macro overnight
The Bank of Japan voted 7–2 to set its overnight call-rate guideline at around 1.25%, effective September 24. Its statement flags the risk of underlying inflation moving above target and ties further tightening to economic, price and financial developments. That follows the Federal Reserve’s September 16 increase of 25 basis points to a 3.75–4.00% target range. Neither decision says that a short-lived decline in oil has settled the inflation problem. [1,2]
December S&P 500 futures were up 0.37%, while December Nasdaq-100 futures gained 0.64%. November Brent was USD 102.55 per barrel, down 2.17%. This combination offers near-term relief for equities: a lower energy bill softens one pressure on margins and household spending. It does not establish that supply disruptions or financing costs have permanently eased. The distinction matters most when a market rebound is being read as an all-clear. [3,4]
| Market | Change | Quote time |
|---|---|---|
| Nikkei 225 | +1.38% | 15:45 JST |
| KOSPI | +2.66% | 15:32 JST |
| Hang Seng | +0.57% | 15:53 Hong Kong |
| FTSE 100 | −0.41% | 08:53 BST |
| DAX | −0.43% | 09:53 CEST |
Asia’s positive readings were not matched by Europe’s early session. That split argues against treating stronger U.S. futures as a uniform global risk signal. The dollar index stood at 100.303, while December gold futures were USD 4,433.60 per troy ounce. Gold’s strength alongside equity futures also resists a simple “everything is risk-on” reading. Different markets are pricing different combinations of inflation, currency and growth risk. [3–5]
The U.S. two-year yield was 4.696% and the ten-year was 4.943%. The official September 17 daily curve puts those maturities at 4.67% and 4.94%, respectively, distinct from the overnight readings. Both daily yields fell from September 16, but they still sit 30 and 16 basis points above September 4. The chart’s message is not “rates are falling”; it is that one session of relief has only partly reversed the earlier rise. [3,5,6]
Bond yields remain above their early-September levels
Annualized yields (%); September 4 versus September 17, 2026. Daily par curve, not overnight quotes.
Source: U.S. Treasury daily par yield curve [6]
Your tickers
- ASTS — Filings after the September 17 close disclosed September 16 sales of 40,000 shares by technology chief Huiwen Yao and 12,000 by operating chief Shanti Gupta. Yao’s sale was under a Rule 10b5-1 plan adopted June 5; these are shareholder sales, not a company capital raise. [12,13]
- PEP — PepsiCo elected Joaquin Duato as an independent director, with board and Audit Committee service effective December 1, 2026. This is a governance development, not an earnings or sales-guidance revision. [11]
The premium seller’s angle
VIX was 15.16 overnight, compared with official closes of 17.71 on September 16 and 15.44 on September 17. The decline signals cheaper broad-market implied volatility, not a guarantee of smaller stock-specific gaps. All else equal, lower implied volatility reduces option premiums; assignment exposure still depends on the stock, strike, time remaining and intervening news. A market-wide index cannot substitute for a particular option’s price or liquidity. [3,5,7]
Cash also retains an opportunity cost: the Treasury’s three-month par yield was 4.12% on September 17, an annualized benchmark rather than a promised brokerage cash rate. YieldCove’s reading is that the rebound improves sentiment without removing the hurdle for taking equity downside risk. Comparing premium income with collateral income still requires consistent time periods, fees and the possibility of owning a falling stock. No live option setup follows from this macro snapshot. [6]
What to watch today
September 18 checkpoints, all in America/Toronto time (EDT): [8–10]
- 09:15 — U.S. industrial production and capacity utilization. The release will add evidence on activity, rather than merely the market’s reaction to policy. [8,10]
- 09:30 — Michelle W. Bowman speaks on stress testing in London. The scheduled topic is banking supervision; it should not be pre-labelled as a monetary-policy signal. [8]
- 10:00 — August state employment and unemployment; 12:45 — New York Fed Staff Nowcast. These are separate regional-labor and growth checkpoints, not another national payrolls release. [9,10]
The next test is whether oil relief survives alongside those activity readings and whether bond yields remain contained. Renewed energy pressure would weaken the relief narrative; firm growth with sticky financing costs would leave the valuation hurdle intact. The BOJ’s September 24 implementation date is the next dated policy step, not a forecast of another rate decision. [1,6]
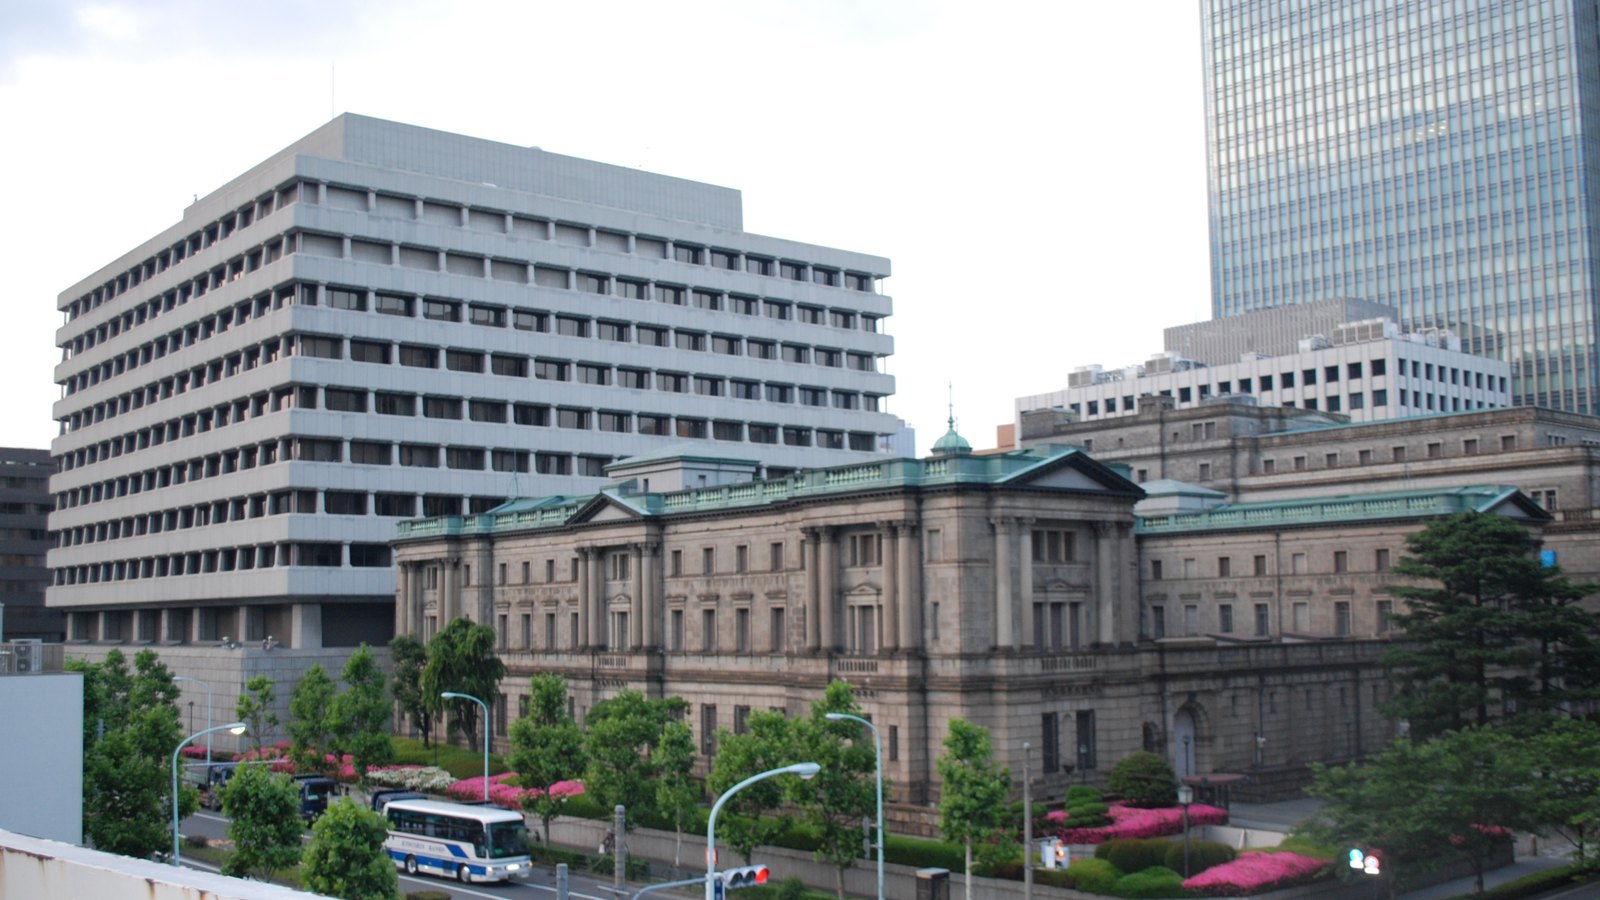
Photograph: Bank of Japan head office, Tokyo, June 2010; katorisi, CC BY-SA 3.0. Cropped and resized; the adapted photograph is shared under the same license. [14,15]
Sources
- [1]Monetary policy decision, September 18, 2026 — Bank of Japan · Accessed 2026-09-18T08:14:08.174728+00:00 · Tier 1
- [2]FOMC statement, September 16, 2026 — Federal Reserve · Accessed 2026-09-18T08:08:30.150632+00:00 · Tier 1
- [3]Global market quotations, September 18, 2026 — CNBC · Accessed 2026-09-18T08:08:30.144594+00:00 · Tier 2
- [4]Futures quotations, September 18, 2026 — TradingView · Accessed 2026-09-18T08:08:30.059186+00:00 · Tier 2
- [5]Global indices and bond yields, September 18, 2026 — TradingView · Accessed 2026-09-18T08:08:30.049277+00:00 · Tier 2
- [6]Daily Treasury par yield curve, September 2026 — U.S. Treasury · Accessed 2026-09-18T08:08:47.139704+00:00 · Tier 1
- [7]VIX daily closing history — Cboe · Accessed 2026-09-18T08:08:30.117889+00:00 · Tier 1
- [8]September 2026 events and statistical releases — Federal Reserve · Accessed 2026-09-18T08:08:30.065056+00:00 · Tier 1
- [9]September 2026 release calendar — Bureau of Labor Statistics · Accessed 2026-09-18T08:08:30.073908+00:00 · Tier 1
- [10]September 2026 economic indicators calendar — Federal Reserve Bank of New York · Accessed 2026-09-18T08:08:30.287286+00:00 · Tier 1
- [11]PepsiCo director appointment, September 17, 2026 — PepsiCo / SEC · Accessed 2026-09-18T08:11:59.578324+00:00 · Tier 1
- [12]Huiwen Yao ownership filing, September 17, 2026 — AST SpaceMobile / SEC · Accessed 2026-09-18T08:12:54.769796+00:00 · Tier 1
- [13]Shanti Gupta ownership filing, September 17, 2026 — AST SpaceMobile / SEC · Accessed 2026-09-18T08:12:54.777560+00:00 · Tier 1
- [14]Bank of Japan head office — archival photograph by katorisi — Wikimedia Commons / katorisi · Accessed 2026-09-18T08:12:49.857998+00:00 · Tier 1
- [15]Creative Commons Attribution-ShareAlike 3.0 license — Creative Commons · Accessed 2026-09-18T08:12:50.190454+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
Read next

Relief spreads, but index options resist the all-clear
The rebound widened as volatility fell, yet index options remained more put-heavy than stock options. For premium sellers, calmer prices do not establish a one-way market.
Futures rebound, but the Fed keeps the funding hurdle high
Equity futures are recovering as oil and volatility ease after the Fed’s rate increase. For premium sellers, the rebound does not erase higher financing costs or the distinction between cash yield and compensation for assignment risk.
Oil eases, but 5% Treasuries keep the Fed-day pressure on
A modest rebound in equity futures is running into stubbornly high bond yields before the Fed decision. For premium sellers, the distinction between temporary oil relief and lasting policy risk matters more than a greener opening screen.