
Relief spreads, but index options resist the all-clear
The rebound widened as volatility fell, yet index options remained more put-heavy than stock options. For premium sellers, calmer prices do not establish a one-way market.
YieldCove Desk
4 min read
The rebound extends beyond technology, but relief is not the same as unanimous conviction. Smaller companies, equal-weighted shares and corporate-bond funds joined the advance while index options remained more put-heavy than individual-stock options. For premium sellers, the useful distinction is between improving market conditions and proof that downside risk has disappeared.
This September 18, 2026 assessment uses completed-session prices from September 17, 2026. Dates are in America/Toronto, Eastern Time; fund prices are in U.S. dollars and daily changes are price returns, not total returns. The central question is whether broader participation can persist after the initial release of tension.
Sentiment scoreboard
$QQQ daily change
+1.73%
September 17 close
$VIX close
15.44
−12.82% daily
Equity put/call
0.52
Cboe volume ratio
Index put/call
1.07
Cboe volume ratio
| Market proxy | Close / change | Interpretation |
|---|---|---|
| $QQQ — Nasdaq-100 | 716.92 / +1.73% | Growth-led advance |
| $IWM — small caps | 285.43 / +0.53% | Smaller companies participate |
| $RSP — equal weight | 213.31 / +0.49% | Gains extend beyond the largest names |
| $HYG — high-yield bonds | 78.72 / +0.38% | Riskier corporate debt also rises |
| $LQD — investment-grade bonds | 105.16 / +0.68% | Higher-quality corporate debt gains more |
Institutional signals: participation improves, conviction stays unproven
The Nasdaq-100 fund outpaced the small-cap fund by about 1.20 percentage points. That still leaves technology-heavy growth in front, but positive small-cap and equal-weight returns make this a different pattern from a rally carried only by the largest companies. Breadth is improving across these proxies; that is not a claim that every sector or most individual stocks rose.
The options contrast is just as important. Cboe reported a total put/call volume ratio of 0.79, an equity ratio of 0.52, an index ratio of 1.07, and a combined $SPX plus $SPXW ratio of 1.15 for September 17. Calls outnumbered puts in individual-stock options, while puts outnumbered calls in index options. These are contract counts, not dollars committed or a direct measure of bullish and bearish investors.
Index derivatives are useful institutional-market indicators, but the ratios do not identify who traded, whether positions opened or closed, or whether a put was bought or sold. A put-heavy index day can coexist with rising shares. The defensible conclusion is coexistence of different exposures, not a story in which institutions secretly sell while retail investors buy. Nor does one low equity ratio establish historically extreme crowding.
Volatility and bonds support relief, not a risk-free market
Cboe’s $VIX closed at 15.44, down from 17.71, a decline of 12.82%. The reversal places the latest close below the preceding observations shown here. As an option-implied volatility measure, it describes the price of expected market variability, not a forecast of the next direction. Lower broad-market volatility can reduce the compensation available from option premiums, all else equal, without removing stock-specific loss risk.
| Date | Closing $VIX |
|---|---|
| 2026-09-11 | 15.84 |
| 2026-09-14 | 17.10 |
| 2026-09-15 | 17.20 |
| 2026-09-16 | 17.71 |
| 2026-09-17 | 15.44 |
Treasury par yields also eased: the two-year yield fell to 4.67% and the ten-year to 4.94%, each down 7 basis points. Their gap remained 27 basis points. Both corporate-bond funds rose, but the larger gain in investment-grade debt is compatible with interest-rate relief, not just greater appetite for credit risk. Fund prices blend rate sensitivity and credit exposure; they do not isolate credit spreads or prove new institutional inflows.
Retail pulse: enthusiasm, distrust and the wish to do less
Individual Reddit discussions on September 17 show a disagreement over what the rebound means. One r/stocks post asks whether to buy the dip or rotate toward energy. Another treats the advance with suspicion and anticipates trouble ahead. Those opposing interpretations matter as expressions of risk appetite, not as evidence that either participant knows the market’s next move. A claim about hidden institutional intent is an opinion, not established positioning.
In r/Bogleheads, the emphasis is different. One discussion asks whether leaving a diversified portfolio alone matters more than repeated optimization. Another questions whether bond dividends should be reinvested or held in cash while interest rates remain a concern. These are personal trade-offs between participation, simplicity and liquidity, rather than a shared prediction about the next session. They also explain why a price rally need not make every investor feel more comfortable.
The retail picture is therefore plural: tactical opportunity-seeking, bearish distrust and a preference for disciplined inaction coexist. These individual views do not establish retail consensus. The useful comparison with market prices is not who is smarter, but whether the desire for upside is accompanied by a realistic willingness to bear a reversal.
Where the signals agree—and diverge
| Theme | Market signal | Retail tension |
|---|---|---|
| Participation | Growth, small-cap and equal-weight funds rise | Dip interest competes with distrust of the rebound |
| Protection | Index options remain more put-heavy than stock options | Bearish language does not prove actual hedging |
| Staying invested | Volatility and Treasury yields decline | Some discussions still favour simplicity or cash flexibility |
For option sellers, improved participation is encouraging, but a lower premium is not automatically a better bargain. The obligation attached to a short put or covered call remains even when the mood brightens. Index-level calm and single-stock risk are different exposures.
What could change the picture
- During the September 18, 2026 session, continued gains in small-cap and equal-weight shares would strengthen the case that the rebound reaches beyond technology. Renewed weakness in those groups would weaken it.
- The next completed-session volatility and options-volume readings can distinguish persistent relief from a temporary reset. Comparable observations matter more than treating a single ratio as a timing signal.
- If corporate-bond gains persist alongside stable or lower Treasury yields, the cross-asset backdrop remains supportive. A reversal in both would challenge the interpretation that financial-market tension is easing.
The strongest counterargument
A broad rebound after pressure can reflect position adjustment rather than durable conviction. Fund composition, rate sensitivity and options trading purposes differ, so apparent agreement across assets is not proof of a common buyer. Conversely, persistent skepticism can survive a genuine recovery. YieldCove’s reading is constructive on participation and cautious on certainty: the rebound has broadened, but neither crowding nor an institutional-versus-retail showdown is established.
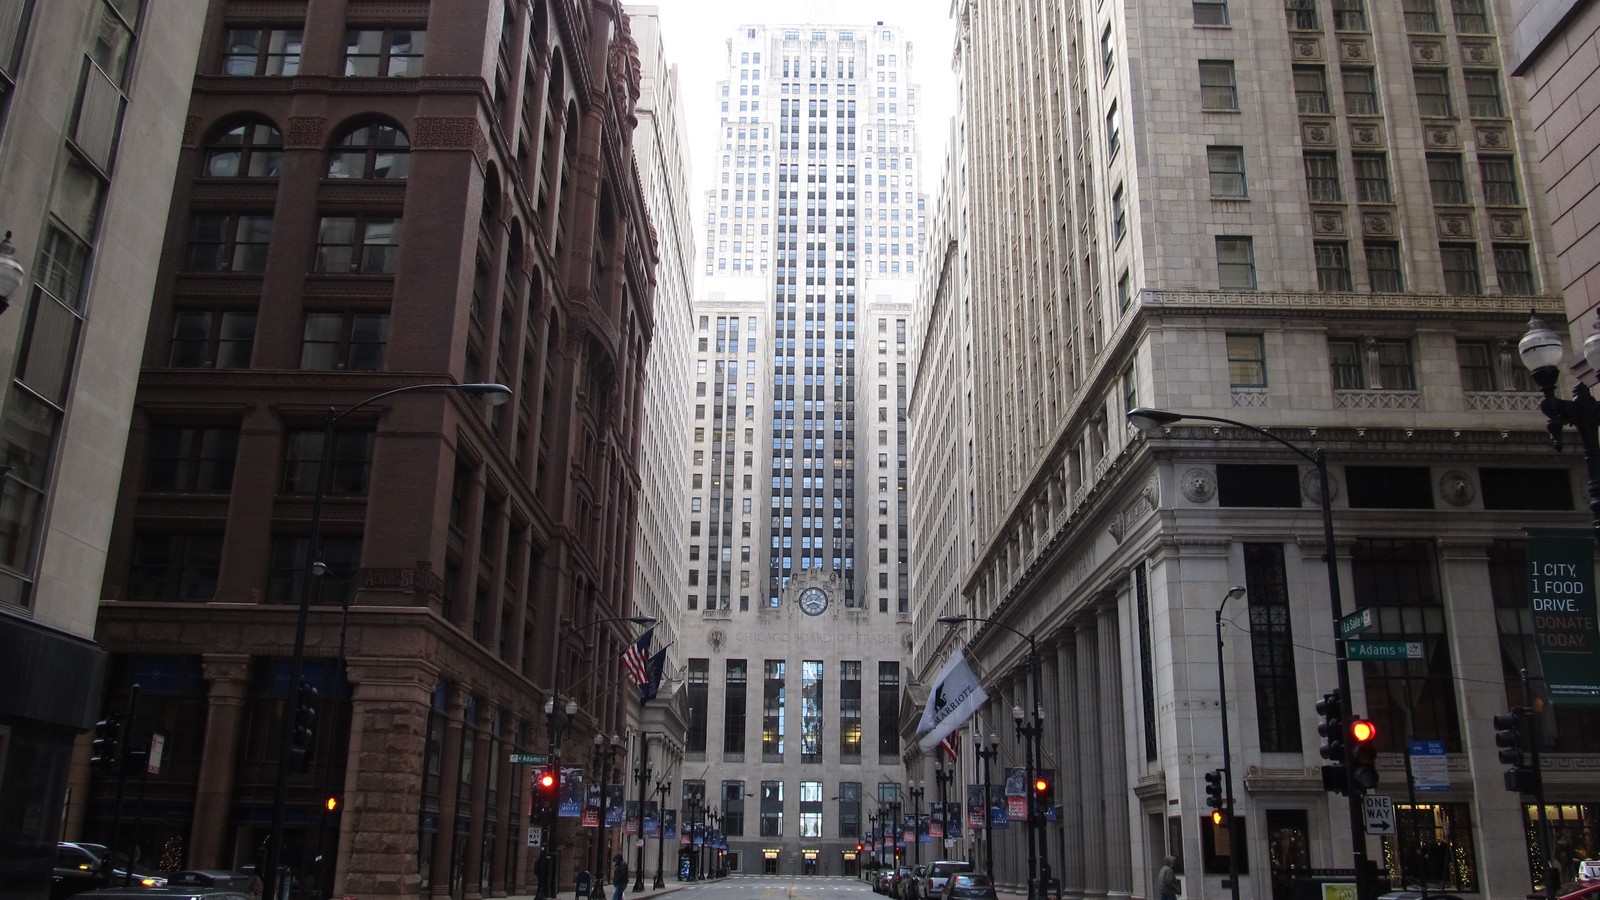
Photograph: Chicago Board of Trade streetscape, November 22, 2013, by Ken Lund. Archival financial-market setting, not the current session. Cropped and resized under CC BY-SA 2.0; the adaptation retains the same license.
Sources
- [1]September 17 fund closes / Clôtures des fonds du 17 septembre — CNBC · Accessed 2026-09-18T09:05:27.141527+00:00 · Tier 2
- [2]Fund prices and changes / Cours et variations des fonds — TradingView · Accessed 2026-09-18T09:05:27.141852+00:00 · Tier 2
- [3]Daily $VIX history / Historique quotidien du $VIX — Cboe Global Markets · Accessed 2026-09-18T09:05:27.142871+00:00 · Tier 1
- [4]September 17 options volume / Volumes d’options du 17 septembre — Cboe Global Markets · Accessed 2026-09-18T09:05:27.144376+00:00 · Tier 1
- [5]Daily Treasury par yields / Taux au pair quotidiens du Trésor — U.S. Treasury · Accessed 2026-09-18T09:05:27.144970+00:00 · Tier 1
- [6]$VIX methodology / Méthodologie du $VIX — Cboe Global Markets · Accessed 2026-09-18T09:05:27.143758+00:00 · Tier 1
- [7]Dip buying or rotation? / Acheter le repli ou changer d’exposition? — Reddit — r/stocks · Accessed 2026-09-18T09:05:27.243630+00:00 · Tier 4
- [8]Skeptical rebound opinion / Opinion sceptique sur le rebond — Reddit — r/stocks · Accessed 2026-09-18T09:05:27.243630+00:00 · Tier 4
- [9]Portfolio simplicity / Simplicité du portefeuille — Reddit — r/Bogleheads · Accessed 2026-09-18T09:06:36.202944+00:00 · Tier 4
- [10]Bond reinvestment or cash / Réinvestissement obligataire ou liquidités — Reddit — r/Bogleheads · Accessed 2026-09-18T09:06:36.202944+00:00 · Tier 4
- [11]Chicago Board of Trade — archival photo / photographie d’archives — Ken Lund / Wikimedia Commons · Accessed 2026-09-18T09:07:59.144016+00:00 · Tier 1
- [12]CC BY-SA 2.0 — photo license / licence de la photo — Creative Commons · Accessed 2026-09-18T09:07:59.393864+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
Read next

Cheaper oil lifts futures, but Japan adds another rate hurdle
Falling oil and stronger equity futures extend the relief rally even as Japan tightens monetary policy. For premium sellers, calmer broad-market volatility must still be weighed against elevated bond yields and company-specific risks.
Tech holds its ground, but market confidence stays narrow
Technology-heavy shares held steady while broader equity measures fell. For option sellers, that split makes participation and downside exposure more useful than a single bullish or bearish sentiment label.
Stock losses expose a split in Fed-day risk appetite
Equity losses coexist with call-heavy stock options and put-heavy index activity. For option sellers, the split shows why trading volume is not a reliable shortcut to investor conviction.