
Oil rebounds into a quiet VIX, testing the AI rally
Oil is rebounding while technology optimism carries into Asia and Europe opens softer. For premium sellers, subdued index volatility does not erase company risk or the competing return available on cash.
YieldCove Desk
3 min read
Brent · November futures [1,2]
USD 101.63
+1.29%
S&P 500 · December futures [1,2]
−0.08%
US 10-year yield [1,3]
4.967%
VIX · September 21 close [4]
14.87
Oil is taking back part of the relief that helped the AI trade rally, while the volatility gauge remains well below its midmonth high. That leaves premium sellers facing an awkward combination: renewed enthusiasm for technology, but less broad-market fear in option prices. The important distinction is between a calmer index and a genuinely safer company. [4,6,7]
Macro overnight
On September 22, 2026, S&P 500 and Nasdaq-100 December futures were slightly lower after the previous US session’s technology-led advance. The observations below span 03:59–04:09 Eastern time, America/Toronto, and include delayed prices; they are a dated market snapshot, not executable quotations. November Brent had rebounded, the dollar was firmer and December gold was lower. [1,2,3,7]
| Market | Level | Change |
|---|---|---|
| S&P 500 · Dec | 7,827.50 | −0.08% |
| Nasdaq-100 · Dec | 30,772.50 | −0.04% |
| Brent · Nov · USD/barrel | 101.63 | +1.29% |
| Gold · Dec · USD/troy oz | 4,339.20 | −1.02% |
| Dollar index | 100.595 | +0.17% |
| US 2-year yield | 4.777% | — |
| US 10-year yield | 4.967% | — |
Asia’s opening surge had lost some force by the end of the Korean session: the KOSPI finished up 0.15%. European cash equities were softer, with the FTSE 100 down 0.22% and DAX down 0.39% at the 03:54 Eastern observations. Japan’s cash market was closed for a holiday. This is not a synchronized global breakout; early enthusiasm and later prices tell different parts of the same night. [1,3,6,7,14]
The central tension remains oil versus financing costs. Hopes for US–Iran diplomacy supported the earlier decline in crude, but that relief has not removed geopolitical supply risk. Nor has it undone the Federal Reserve’s September 16 increase of 25 basis points, which took its target range to 3.75–4.00%. The Fed’s statement explicitly says inflation remains elevated. A better oil headline does not by itself reverse that policy backdrop. [6,7,8]
VIX has cooled from midmonth stress, not eliminated it
Daily closing points, September 8–21, 2026. A broad index gauge, not a single-stock option quote. [4]
Source: Cboe · daily VIX history · accessed September 22, 2026 [4]
The VIX closed at 14.87 on September 21, versus 17.71 on September 16. That retreat describes cheaper broad-market protection relative to the recent stress point, not a forecast of tomorrow’s move. Single-stock implied volatility can still reflect product, earnings or financing risks absent from the index. Without a current option chain, there is no defensible conclusion here about a particular strike’s premium or return. [4]
Your tickers
META — product optimism, not an earnings release. Overnight reporting linked renewed AI enthusiasm to Muse, the personal agent Meta introduced on September 8. Meta describes a service that carries out tasks, with free access and subscription plans. The market’s adoption story is real; durable paid usage and profit are the next economic tests, not conclusions that download enthusiasm can settle. This is a continuing catalyst rather than a newly announced overnight product. [6,9,10]
The premium seller’s trade-off
Less index fear need not mean better compensation for taking equity risk. The September 21 Treasury three-month par yield was 4.17% annualized, a useful cash benchmark—not a broker’s promised collateral rate. Put sellers still absorb downside if shares fall through their strike; covered-call sellers exchange upside participation for premium. Oil, rates and company catalysts can change those trade-offs independently. A quiet VIX therefore argues for separating cash income, option income and the underlying business risk rather than treating them as one yield. [4,5]
What to watch today
| Time | Checkpoint | Why it matters |
|---|---|---|
| 08:30 | Philadelphia Fed non-manufacturing survey | Services-sector demand and pricing signals |
| 10:00 | Richmond Fed manufacturing survey | Regional factory demand and costs |
| 10:05 / 10:20 | John Williams / Philip Jefferson | Treasury-market conference remarks |
| 16:15 | Fed H.15 interest-rate release | Updated official rate references |
The useful test is whether softer oil and stable borrowing costs can reinforce the technology rebound, rather than merely accompany it for a few hours. Regional surveys provide a separate check on demand and pricing. A renewed oil rise alongside persistent high yields would make the calm volatility reading less reassuring; the bullish alternative is relief that survives both the data and the policy discussion.
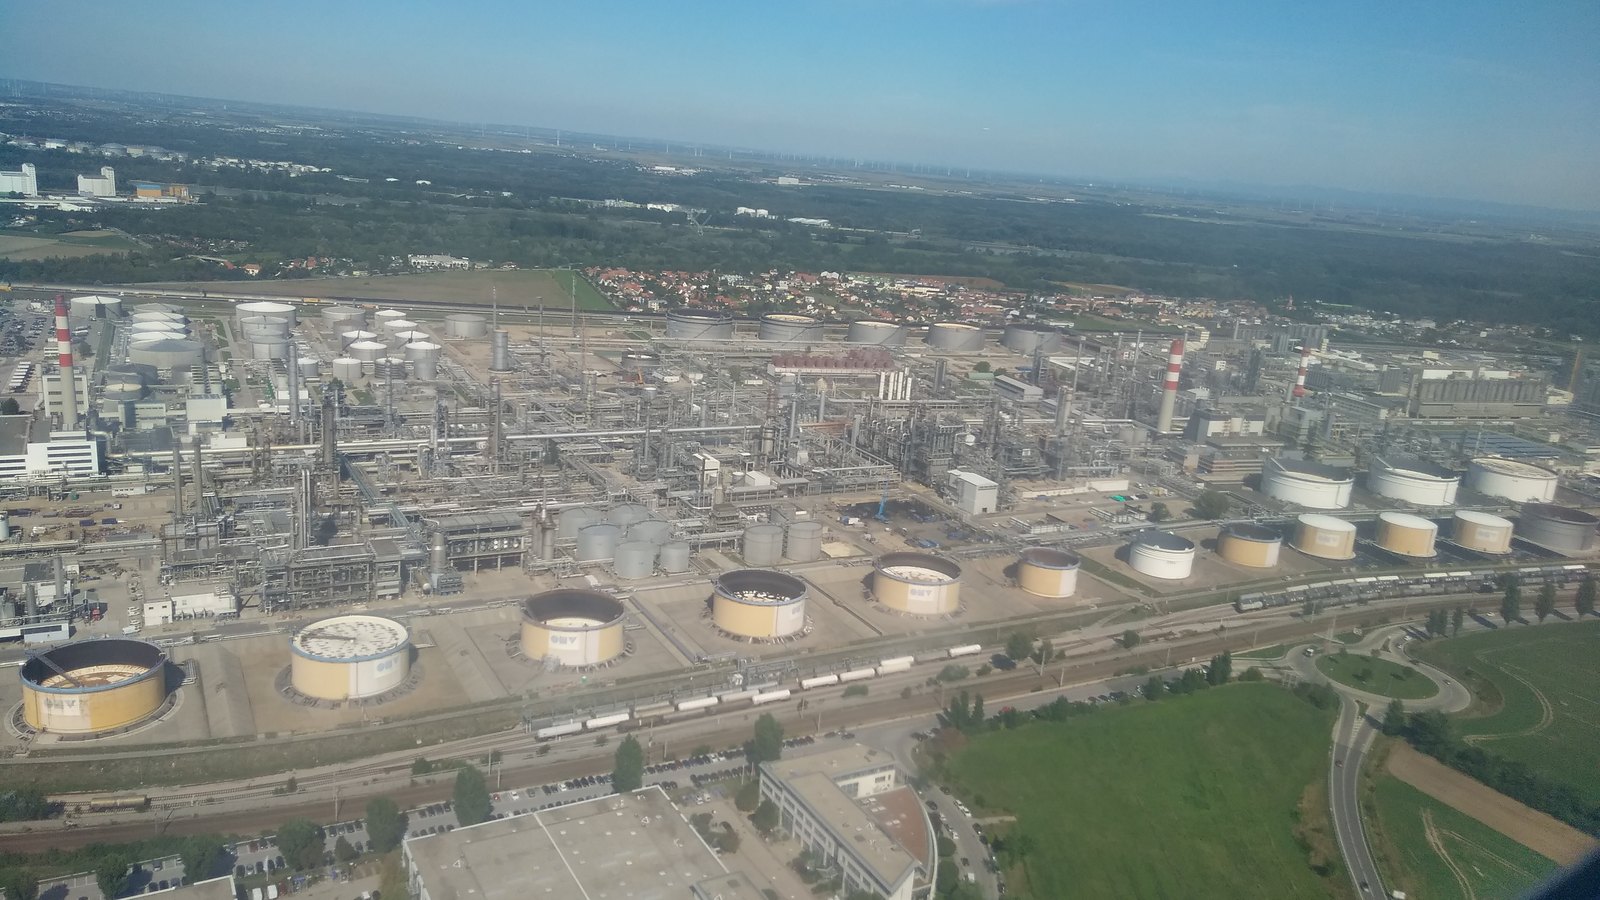
Photo: archival aerial view of the Schwechat refinery near Vienna; not a photograph of current Middle East events. Remi Mathis / Wikimedia Commons, CC BY-SA 4.0; cropped and resized. [15,16]
Sources
- [1]Overnight futures, currencies and bond observations — CNBC · Accessed 2026-09-22T08:09:41.714364+00:00 · Tier 2
- [2]Futures market observations — TradingView · Accessed 2026-09-22T08:10:16.846566+00:00 · Tier 2
- [3]Global index, currency and bond observations — TradingView · Accessed 2026-09-22T08:10:16.959749+00:00 · Tier 2
- [4]VIX daily historical prices — Cboe · Accessed 2026-09-22T08:09:41.721404+00:00 · Tier 1
- [5]Daily Treasury par yield curve rates — U.S. Treasury · Accessed 2026-09-22T08:10:00.657896+00:00 · Tier 1
- [6]Tech rally boosts Asian stocks, dollar firms on rate-hike wagers — Reuters via Euronext · Accessed 2026-09-22T08:09:42.143461+00:00 · Tier 2
- [7]Stock futures are little changed after the Wall Street rally — CNBC · Accessed 2026-09-22T08:09:42.109896+00:00 · Tier 2
- [8]Federal Reserve issues FOMC statement — September 16, 2026 — Federal Reserve · Accessed 2026-09-22T08:09:41.715250+00:00 · Tier 1
- [9]Introducing Muse: a personal AI agent — Meta · Accessed 2026-09-22T08:18:55.029444+00:00 · Tier 1
- [10]Meta’s Muse app and the renewed AI trade — CNBC · Accessed 2026-09-22T08:12:20.285167+00:00 · Tier 2
- [11]September 2026 economic indicators calendar — Federal Reserve Bank of New York · Accessed 2026-09-22T08:09:41.807903+00:00 · Tier 1
- [12]The 2026 U.S. Treasury Market Conference — Federal Reserve Bank of New York · Accessed 2026-09-22T08:12:20.840431+00:00 · Tier 1
- [13]September 2026 Federal Reserve calendar — Federal Reserve · Accessed 2026-09-22T08:09:41.715188+00:00 · Tier 1
- [14]Market holidays in 2026 — Japan Exchange Group · Accessed 2026-09-22T08:09:42.071497+00:00 · Tier 1
- [15]Schwechat refinery — archival aerial photograph — Remi Mathis / Wikimedia Commons · Accessed 2026-09-22T08:16:15.316014+00:00 · Tier 1
- [16]Creative Commons Attribution-ShareAlike 4.0 license — Creative Commons · Accessed 2026-09-22T08:16:15.582793+00:00 · Tier 1
This content is for informational and educational purposes only and is not financial advice. Options involve risk and are not suitable for every investor. Do your own research before trading.
Read next
Cheaper oil lifts futures, but bond yields keep the hurdle high
Futures are rising as oil retreats, yet elevated bond yields keep the cost of taking equity risk in focus. For premium sellers, fresh financing filings show why a calmer index does not mean safer individual stocks.
Relief spreads, but index options resist the all-clear
The rebound widened as volatility fell, yet index options remained more put-heavy than stock options. For premium sellers, calmer prices do not establish a one-way market.
Cheaper oil lifts futures, but Japan adds another rate hurdle
Falling oil and stronger equity futures extend the relief rally even as Japan tightens monetary policy. For premium sellers, calmer broad-market volatility must still be weighed against elevated bond yields and company-specific risks.